
By: Christian Collington, Local Journalism Initiative Reporter, TheIFP.ca
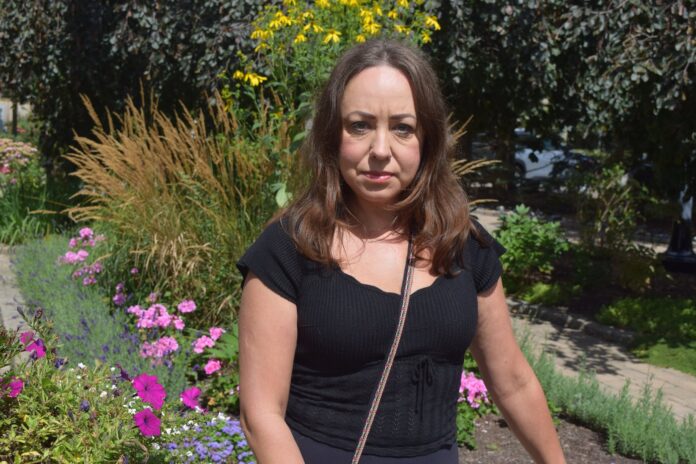
When a fire destroyed Antonina Gladkova’s home in February 2024, it sparked a gruelling ordeal that left her determined to expose hidden traps in standard mortgage agreements.
She said her insurance company quickly approved a full $508,000 rebuild of her Georgetown home. But when her lender, Simplii Financial, refused to release the funds alongside her contractor’s invoices, the relief turned to frustration.
Instead of paying the contractor’s $101,600 invoice, Simplii released just $25,000 — then another $25,000 a month later.
Desperate to keep construction moving, Gladkova took on a $175,000 private mortgage. Today, she carries $50,000 in remaining debt.
A mathematical trap
Because Gladkova held a mortgage, Simplii financial held the legal rights to the insurance payout.
She said after she escalated an internal complaint with Simplii in July 2025, the bank switched to a “percentage-of-completion” model. But the bank calculated progress using only a $320,000 advance cheque instead of the full $508,000 claim, creating a constant shortfall.
“You cannot build without the money. So it’s like a chicken and egg situation,” Gladkova said. “It became worse. We were absolutely outraged.”
By September 2025, with work stalled, Gladkova had to secure the $175,000 private mortgage.
Simplii Financial did not respond to requests for comment by publication deadline for this article.
The hidden power of mortgage lenders
Gladkova’s experience exposed a critical gap in homeowner understanding: when property is damaged, the lender — not the homeowner — controls the insurance money.
Meghan Symons, a mortgage broker at BRX Mortgage, noted that this arrangement frequently catches clients off guard.
“Your mortgage and insurance are two separate contracts, but they are connected by the same asset, which is the home,” Symons explained. “The mortgage company has a financial interest in the property, so you shouldn’t make the assumption that if there is a claim, you are entitled to either pay off the mortgage or get the cheque yourself.”
Because lenders are listed as primary payees on insurance policies, Symons said they retain full authority to disburse funds on their own terms.
“It really depends on how the insurance company and the lender are communicating together,” Symons said. “It is not a guarantee that you will get the cheque.”
Regulatory gaps and communication breakdown
Seeking help, Gladkova filed a complaint with the Ombudsman for Banking Services and Investments (OBSI) in December 2025.
By June, Gladkova said OBSI closed its investigation and recommended Simplii compensate Gladkova $500 for causing “extraordinary distress and inconvenience” by not explaining that she may need additional financing to complete the rebuild, but Gladkova did not accept it.
“It was a slap in the face,” she said.
In a statement, OBSI said it received 588 mortgage-related complaints in 2025, representing 11 per cent of all banking cases. However, they also stated that they do not separately track complaints about insurance fund delays.
Additionally, while the organization stated it has “never had a recommendation rejected by a participating bank,” its decisions are not binding. If a firm refuses a recommendation, OBSI can only publicly name the firm and publish details of the case.
However, OBSI noted that “securities regulators in Canada are actively advancing a policy initiative to make OBSI decisions binding for investment complaints, but these initiatives are not yet in force.”
The Financial Services Regulatory Authority (FSRA), which oversees mortgage lenders in Ontario, does not directly regulate a lender’s contractual administration of insurance proceeds.
According to FSRA, “FSRA cannot resolve contractual disputes, award compensation or order the release of funds.”
The financial fallout
While the primary insurance funds were eventually released, the delays inflicted severe economic damage including $50,000 remaining in private mortgage debt, $40,000 spent strictly on private financing fees and setup costs and $19,000 in additional contractor fees.
The rebuild was completed in June, six months behind schedule.
What homeowners should know
Symons encourages homeowners to understand what the lender’s insurance clause says before signing a mortgage.
She also recommends before construction on a rebuild begins, homeowners should ensure all parties — lender, contractor and insurance company — are aligned on payment schedules.
“Making sure that they’re leaning on their mortgage professional who can explain the lender’s requirements,” she said. “But then they should also be relying on their licensed insurance professional for advice.”
According to OBSI, “homeowners should understand that mortgage documents give lenders certain rights with respect to insurance proceeds paid following damage to a mortgaged property.”
Gladkova said that she now rents out the property and has a new 30-year mortgage under RBC, however she advises homeowners to read their mortgage agreement, understand what rights the lender has over insurance proceeds and ask questions before signing.
“No one should experience this as it was life changing,” she said.